Victoria’s Secret Hollywood Showing Up For Fashion Show
Published
The Angels are back … and Hollywood’s biggest stars are bringing some serious heat to the Victoria’s Secret Fashion Show 2026.
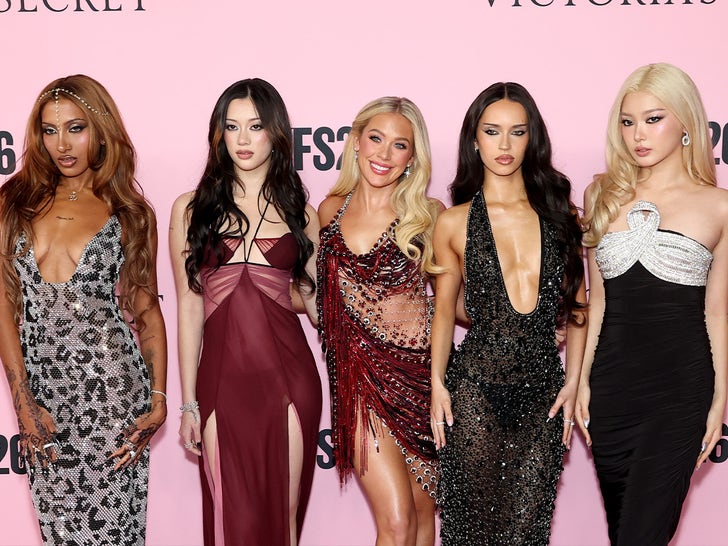
Megan Thee Stallion, Tate McRae and Livvy Dunne were among the famous faces turning heads on the pink carpet Sunday at Sony Pictures Studios in Culver City, California.
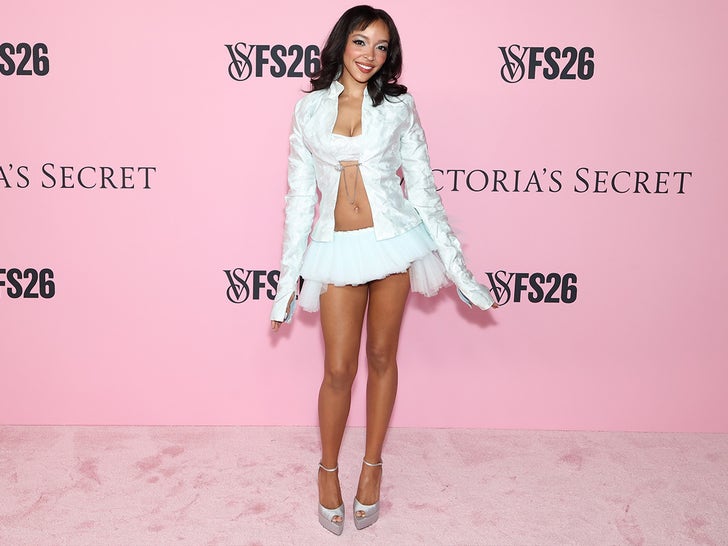
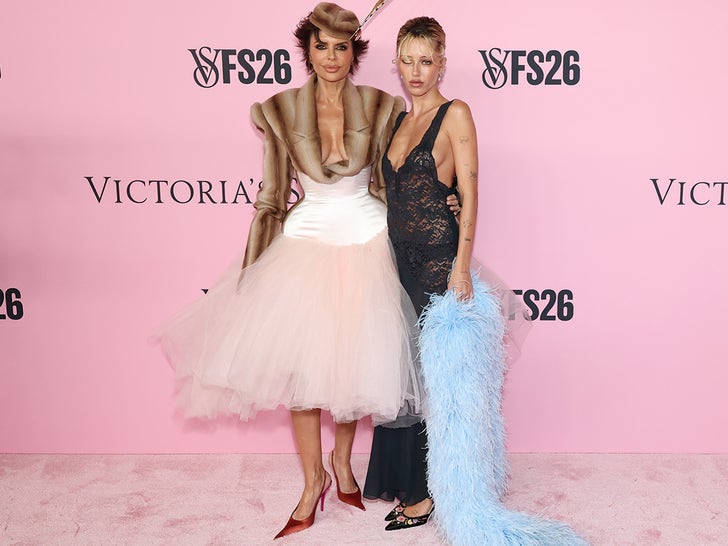
Tinashewas also showing plenty of leg in an all-white ensemble … while Lisa Rinna and daughter Delilah Belle Hamlin made it a family affair, striking a pose together in contrasting looks.
And the star power doesn’t stop at the carpet … Gigi Hadid, Adriana Lima, Ashley Graham and Barbara Palvin are among the models taking over the runway.
Megan and Tate are also pulling double duty … joining Megan Moroney and KATSEYE as this year’s musical performers.
The fashion extravaganza is back in Los Angeles after two years in New York City … and judging by the arrivals, these celebs came dressed to impress.
Backstage, the Angels were getting the full glam treatment … with hair rollers, makeup touch-ups and plenty of playful moments before hitting the runway.
Click through the gallery to see all the famous faces spreading their wings at this year’s show!
The players sometimes change. I sat down with four of Benchmark’s partners three years ago, and three of those individuals are no longer with the firm. The capital commitments have changed, too. This summer, Benchmark announced $2 billion across two funds, marking only the second time in its 31-year history that it has veered from raising a far smaller vehicle.
But at this week’s TechCrunch Disrupt, the venture firm’s five partners convincingly portrayed a close-knit team that’s not about to put the pedal to the metal, even as many of their rivals do exactly that. The world may be speeding up, but they’re investing at the pace Benchmark always has: just two or three new bets per year per partner. The world is drowning in information, yet their Monday partner meetings still have no agenda. And while economic indicators point to trouble ahead, they don’t seem too bothered, seeing many of the warning signs as products of X-fueled hysteria.
Here’s what Benchmark’s five general partners — gathered together on our stage — had to say at the show. Some of the comments below have been edited for length and clarity; you can watch the full interview at the end of the article.
Benchmark has evolved in some ways, including a bigger core fund and a new growth fund. How do you think about adapting without losing what makes you Benchmark?
Peter Fenton: The craft that hasn’t changed is the core fund: working closely with founders at the beginning. It’s usually a 10-to-15-year commitment, [working] shoulder to shoulder, and that doesn’t scale. There’s also been inflation. We held the core fund at $500 million for 20 years, and it has just inflated to be consistent with the existing economy, which we hadn’t done and that was probably a tactical error on our part.
[As for the growth fund] it’s an expansion of our mandate. In some ways, we get permission from the ecosystem to do more than just the core early-stage business. [Not having this previously] was a fork in our eye. A number of opportunities that came to Benchmark would have returned somewhere between 10 and 1,000x to Benchmark, and we were constricted by our early-stage focus.
Are you thinking to make handful of bets with that $1.25 billion growth fund?
Fenton: We all have different answers, which is the beauty of a partnership. I’d love for us to have, as that great J.P. Morgan paper puts it, the agony and ecstasy of a concentrated portfolio. If the fund is successful, one or two investments will generate 90% of the returns. So I think it’s four to six, maybe seven to eight.
Ev, you joined Benchmark late last year. You’ve worked at Founders Fund, Bond, and Kleiner Perkins. How does Benchmark differ?
Ev Randall: Every firm is ultimately a collection of the people within the firm and how they work together. Some are very hierarchical, with a 50- or 60-person investment team and investment processes that are federated into product groups. And then you have small partnerships. Very early in my career, I was drawn to small partnerships because they allow a higher level of throughput and fidelity in your conversations, where you don’t feel like you’re making decisions through some Byzantine corporate structure. You’re going out on the field together, like a sports team.
And then the other piece is: You have to find your people, You have to find people who you not only like but admire. With Benchmark, with the current crop of GPs, it was obvious that everyone liked each other and got along, but it went deeper than that. It’s a group that admires each other and learns from each other. That mix of attributes is very rare, and when I saw it, I immediately wanted to join, and I think Jack felt the same way also as a newcomer.
Jack, you joined in February, but it was just a year ago that you raised a second, $275 million fund for your own firm in what you told the Wall Street Journal took one week. You have a hugely popular podcast. Why join Benchmark?
Jack Altman: It’s funny. I did the podcast with these guys at the start of this year, and during that podcast, obviously we talked about the commitment to being a small fund, but more than that, what I heard was that they want to be the first people who founders call, they want to be concentrated, and they just care. So much in this industry gets tied up in money and status, and what I felt from the Benchmark team then, and ten times more as I’ve gotten to know them so well, is it’s a group that really cares about founders and helping companies. And I did enjoy being an individual investor. . .but in a market this crazy, I don’t know how I’d feel, figuring it out on my own. Having a group of people who are so smart and focused and driven to learn it with and from has been awesome. There’s no better place to learn.
I’m told you meet on Mondays with no agenda.
Chethan Puttagunta: Jack tried to make an agenda. [Laughs.]
Altman: I’ve got an agenda for next Monday.
Eric Vishria: It’s weirdly arbitrary, honestly. It’s an ongoing conversation. In a time of rapid change, you’re trying to figure out what’s becoming possible that wasn’t possible six months ago, and who’s bending light. We talk about what companies we’re meeting, what piqued our interest and why, what we’re seeing in board meetings. You can try to systematize it, but one of the beauties of five people is you don’t have to. It’s a decades-long conversation that only works if you’re small and actually enjoy spending time together. After this session, we’re having dinner with one of the very few entrepreneurs who has built a multi-hundred-billion-dollar company, someone we’re not invested in, just to stretch our thinking.
Puttagunta: Part of not having an agenda is you need space to be reactive. If a founder needs help landing an executive or a strategic partnership, the five of us can be at their disposal.
You’re an equal partnership. Can one person put the kibosh on a deal?
Puttagunta: Nobody knows. We don’t have rules around it.
Altman: I actually don’t know. I was waiting to see what someone else [said].
It’s never happened?
Altman: Because the firm is structured around a low volume of deals, you don’t actually want to have all of this rigor. If we invested in 100 or 200 companies a year, you’d want a CRM and a formal voting process. Because it’s so rare, the lack of structure is a huge asset.
Fenton: One of the differentiating aspects of our brand is we’re not so cocksure to come in and say ‘winner’ or ‘loser.’ It’s not Shark Tank. We sort of feel awe, for lack of a better term, at all the possibilities . . . The occasional case where someone comes in who’s polarizing — the entrepreneurs feel that. If someone in the room doesn’t like you, we’re not a great partner.
Companies are growing faster than ever. I’d think it’s easier to feel you’re missing out on opportunities if you don’t invest with greater frequency. Have you picked up the pace?
Puttagunta: I think the pace is consistent. I think part of the reality of venture capital in our business is that we are not going to be part of every successful company, and that’s okay. There are companies that we identify, we find that the entrepreneur has some great strength, and we want to amplify that strength. And it’s our job to find a way to work with that person. It kind of doesn’t matter how much capital they want to raise, or what structure, or where they are. You just have to work through all that stuff.
One thing that founders are interested in as a trend is VCs backing competing companies. Has that VC-founder pact changed because companies are growing so quickly and expanding into one another’s territory?
Vishria: One of the things we have an ethos around is, we are making a commitment to an entrepreneur, and through that commitment, we’re saying we’re going to work with you in this thing, and whatever that thing is, and we are working closely enough where it matters, and it should matter to them, and as it matters to us. The harsh reality of this world is every company is evolving very quickly, and so you do have companies that will naturally evolve from one thing to another, or pivot or change, and you are going to get conflicts. That’s just the reality of the of the kind of current dynamic. . .
Of course, we’re maintaining confidentiality and doing those things and fortunate to not end up in in that type of insane direct conflict [as happened recently with rival companies Factory and Cognition]. . . that commitment of exclusivity in that area is really important. But things are evolving. There’s no doubt about that.
Puttagunta: And I think people are ultra ambitious in this AI era. As the cost of coding new products effectively goes to zero, founders see a surface area and they want to attack the surface area, and so I think it’s probably going to happen more, where you start to run into each other. But there’s a way to be there’s a way to maintain that relationship and be respectful.
Jack, have you made an investment for Benchmark yet, and if so, did you feel a lot of pressure with that first deal?
Altman: I have, a few, and some are recent, so not all are disclosed. My background was software, but since joining, I’ve done chips, robotics and infra. Someone asked me when I joined, ‘How was the onboarding?’ And I was like, ‘It was perfect. There was no onboarding.’ Either Chethan or Eric told me early on, ‘Hey, you’re going to feel tight on your first one. Don’t. You’re going to make many investments while you’re here. This whole game includes crazy power laws. The odds of it being your first are low.’ . . . I trusted they understood what my shape was as a person, as an investor, and I was going to just try to stay as consistent to that as I could.
It really is a group dynamic on a lot of these. The investments I’ve made, I don’t think we would have won them if I didn’t have my partners. I don’t know that I would have been able to know how to get to a yes without them.
Eric, the AI chip company Cerebras was an unusual bet for Benchmark at the time it was made. What persuaded you to move forward with it?
Vishria: We invested in the spring of 2016, in the first round. We hadn’t made a hardware investment in 10 years. The founders seemed good, they had a very simple thesis, and I didn’t understand most of the rest. On the Sunday night before they came back to pitch the partnership, Peter told me it went against everything he’d learned in venture. Then, after the Monday pitch, he had flipped. A big part of it is understanding each other’s instincts. That began a journey of lots of ups and downs and many potential deaths of the company along the way, and it’s far from over. The romanticism of falling in love with a founder and an idea is why we do this.
Fenton: Andrew and his co-founders are heretics. What they were saying was unorthodox, and you see it today, with people dumping on the stock because it’s polarizing. That’s exactly where we have to be as investors. If it’s consensus, why is there a startup?
On that point, Cerebras priced at $185 when it went public earlier this year, jumped to $350, and is back near $185. Why?
Vishria: About six weeks before the IPO, I showed the company stock chart after stock chart: CoreWeave, Datadog, DoorDash, Amazon. Peak to trough, it’s insane how many of them move 500% in a year, up and down. So who knows? You control what you can control, and you update the public markets every 12 weeks. Being a public company takes a stomach of titanium, and the employees have to understand that.
Your former colleague, Bill Gurley, long argued that the traditional IPO process is broken, that that IPO ‘pop’ benefits bankers and their clients — not the company. He’s a proponent of direct listings. Does anyone here agree with that thinking?
Vishria: I think maybe of this group, I’m the only one who’s worked on a direct listing. It can for sure make sense. I think the reality is for this crop of AI companies, it’s going to be unlikely because they need capital, and they need a lot of capital. At the end of the day, IPOs raise money. Cerebras raised $6 billion. That matters, so I think it’s probably unlikely for this crop just because most of them need capital.
Could a severe correction be coming? A lot of AI companies have exhausted their free cash flow. It’s very expensive for companies to borrow. We also just saw the first AI bankruptcy with Character AI.
Randall: Macro is always a fool’s errand to predict with precision. What has changed most since I started investing is the information environment. Character.AI was the leftover corpse of a company whose founder and team were acqui-hired into Google a year and a half ago, and it was already sold for $2.3 billion; its Chapter 11 being read as an AI chill effect shows that the info environment for public equities in tech has been drawn so much into this, like, hyperactive X echo chamber.
If you look at the market today and you see where CoreWeave and Nebius and all these things are trading, those numbers are are due to the ARR figures of two private companies that will probably be public in the next 12 months . . .There’s so much capex and there’s so much investment that runs through the estimated and projected health of OpenAI and Anthropic.
Our companies see so much demand that they can’t get enough compute to serve customers who are willing to pay them at good gross margins. There’s nothing inherently unhealthy about the AI ecosystem. What’s unhealthy is the volatility from data points that are often untrue or exaggerated for clicks. I do think OpenAI and Anthropic going public would be healthy, so the market stops swinging 5% to 10% every time an anonymous account updates an estimate.
Those two companies have also really pulled the center of gravity back to San Francisco. Do you have to be in San Francisco to be a founder now? Are you interested in companies outside of California?
Altman: I don’t know that you have to be here as a founder, but I think it is right now by far the easiest place to get talent, capital, and customers. Probably everyone [on the team] works with companies that are not in San Francisco, but we’re also here in San Francisco every day, so I wouldn’t say you have to, but I’d say: strong bias for our particular setup.
Fenton: Historically, 90%-plus percent of the capital returns have come from companies founded here. There are beautiful stories outside that dense probability distribution — Shopify is a great example, Ramp — but the ecosystem effect that occurs when you have a successful company and that leads to a background of great executives [and] ambitious people, the bar of success gets raised. I don’t think it has systemically happened anywhere quite like here.
Randall: I’m trying to think of a non-SF based company that I’ve met with in the last 18 months that wasn’t actively saying that they were spending time in San Francisco. They’ve either opening an office in San Francisco, they’re spending half of their time in San Francisco, or they’re planning to move out to San Francisco. Iron sharpens iron. If you want to be around peers who are going to make you the best version of yourself, and it’s hard to think of a city that does that better than San Francisco in the current era that we’re in now with AI here.
When you purchase through links in our articles, we may earn a small commission. This doesn’t affect our editorial independence.
Big things come in small packages, and the 650 Battery is no exception! Stylish and discreet, this battery can hold its own in both private and public use, and its sleek design maintains a low profile whether in use or stowed away. With two colors that’ll go with anything, and a 20-second auto-shut off to save you from distractions, your vape is in excellent hands. Smoking on the go has never looked so good!
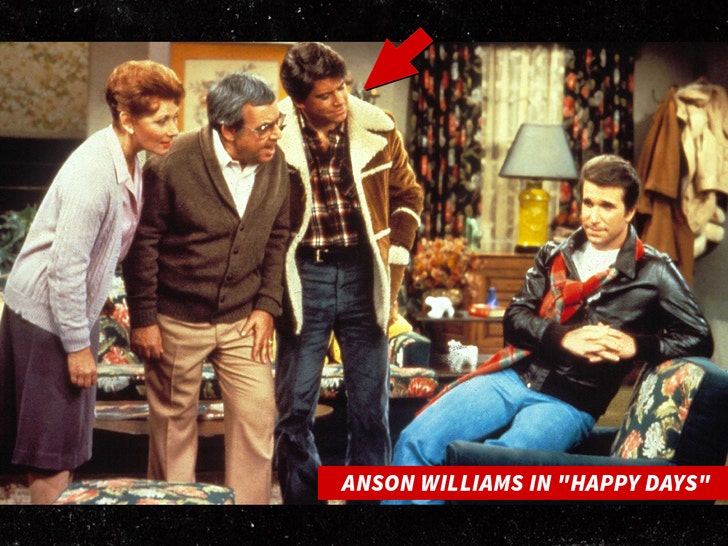
‘Happy Days’ Anson Williams Not-So-Happy Ending to Divorce Drama … Judge Orders $40K to Ex
Published
“Happy Days” star Anson Williams is facing some not-so-happy news in court … a judge has ordered him to cough up more than $40K to his ex-wife over unpaid divorce obligations.
According to court documents, obtained by TMZ, Anson must pay his ex, Jackie Williams, $40,181.04 … plus another $7,500 directly to her attorney, bringing the total bill to nearly $48K.
And he’s got a deadline … the judge ordered Anson to pay everything by 5 PM on November 2.
The money covers several expenses the judge found Anson failed to pay, including nearly $18K in life insurance premiums, roughly $17K in unauthorized use of company funds, and another $2K in payments he made to himself.
The judge also ordered Anson to transfer 160,214 American Express rewards points to Jackie … so she’s getting more than just cash out of this deal.
The docs say Anson didn’t show up for the October 1 hearing or file a response to Jackie’s claims.
As TMZ previously reported, Jackie dragged Anson back to court in August, claiming he’d failed to make payments required under their divorce agreement. She also claimed he ignored her attempts to collect the money.
The former couple divorced in 2020 after 30 years together … but clearly, their financial drama didn’t end with the marriage.
There are countless ways to smoke weed. Some of us prefer cannabis wrapped in rolling papers, some enjoy taking hits from a glass bowl or a one-hitter, and sometimes a bong just feels like the only way to go. But, there’s one method that has quickly become one of the most popular cannabis consumption methods on the market: vaping. Watch as we show you how to make homemade vape oil you can use with your favorite oil vapes.